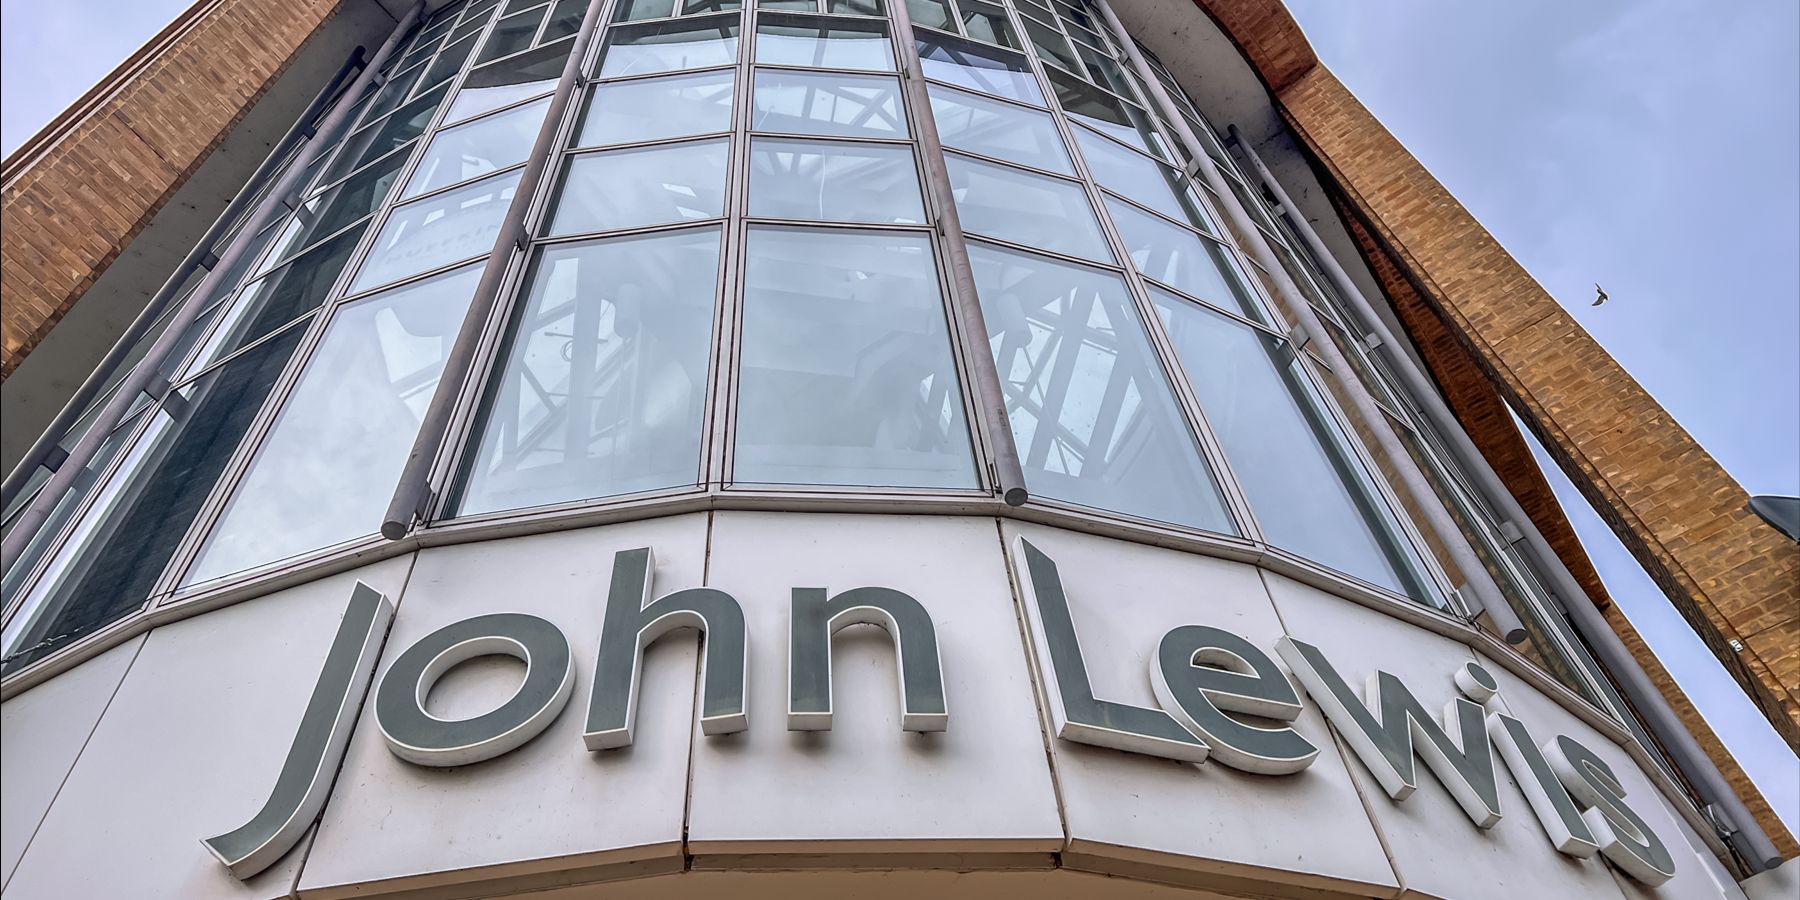
Last week was a disappointing occasion for the John Lewis Partnership. The company recorded losses before tax of £124 million (2025/26: £88m) for H1 2026/27.
Sales at John Lewis were down 2% to £2 billion, and bolstered by sales at Waitrose, which grew 4% to £4.3 billion.
Despite this, JLP’s chairman Jason Tarry said he had confidence that the partnership would rebound. “Our first-half results reflect our continued investment in our transformation, a more challenging trading environment and the increased costs of doing business,” he said. “Partnership sales grew, customer satisfaction remains strong and the stores we’ve transformed are outperforming the rest of our estate. That gives us confidence in the commercial headroom for both Waitrose and John Lewis.’
Transformation under Jason Tarry
When Tarry took over as chairman from Sharon White in 2024, he inherited a business that had turned a profit for the first time since the beginning of Covid, with a strong balance sheet and record investment plans. Much of the difficult job of restructuring was done on White’s watch. What she had not solved, however, was the question of growth. JLP was still wrestling with fundamental questions: How much should future growth come from Waitrose versus John Lewis? How can the business generate consistently attractive returns?
Tarry’s challenge was to transform a repaired and restructured business into a sustainably growing one, and to that end, he has invested significantly in improving the customer experience. The H1 financial statements points out that JLP has accelerated its refurbishment programme, rolled out electronic shelf edge labels, modernised technology, including automation across our supply chains, and invested in inventory management systems to improve availability and reduce waste. “Alongside this we are evolving our central structures so we run a simpler head office and protect investment in stores,” it adds. “We’ll see the benefits of these investments build through the second half.”
What is influencing JLP’s results?
But the H1 2026/27 results show that external factors have as much of an influence on retail results as internal ones – something Tarry himself acknowledged by calling on the government for support. “We want the government to deliver against their manifesto, which is to reform business rates,” he said in a media briefing. “It is the biggest business tax that we face, and in some locations it is bigger than our rent bill.”
Business rates are far from the only factor affecting retailers. Discretionary sales have been hit by the repeated summer heatwaves, which led to a decline in footfall across high streets and stores, as well as an ongoing lack of consumer confidence as conflict in the Middle East persists and the economic outlook remains muted.
Robyn Duffy, an analyst at the consultancy RSM UK, told the Guardian that – despite Tally’s optimistic outlook – John Lewis looks vulnerable heading into the second half. “The retailer is particularly exposed to big-ticket, deferrable categories like home, furniture and electricals – exactly where these consumers are choosing to cut back or delay spending,” she said.
However, the key problem for John Lewis might be more fundamental than that: how viable are department stores in today’s digital world?
The idea of being able to buy everything under one roof has become less of a compelling attraction for shoppers, who can now buy fashion, beauty products and homewares from a huge range of specialists online – or indeed from huge platforms like Amazon. As a result, John Lewis is now one of the UK’s few remaining department store chains, following the disappearance of House of Fraser and Debenhams from Britain’s high streets. Some, like Debenhams and Rackhams, have re-emerged in online-only form. Is this the fate that eventually lies in store for John Lewis?
Ultimately, John Lewis’s problem may not be one of execution but of relevance. Tarry can modernise systems, refurbish stores and lobby for business rates reform, but he cannot turn back the clock to an era when department stores were the default destination for shoppers. Two years into his tenure, the question is no longer whether John Lewis can cut costs or improve operations. It is whether the department store model can still deliver sustainable growth in a digital-first retail landscape.
Stay informed
Our editor carefully curates two newsletters a week filled with up-to-date news, analysis and research. Click here to subscribe to the FREE newsletter sent straight to your inbox. Why not follow us on LinkedIn to receive the latest updates on our research and analysis?